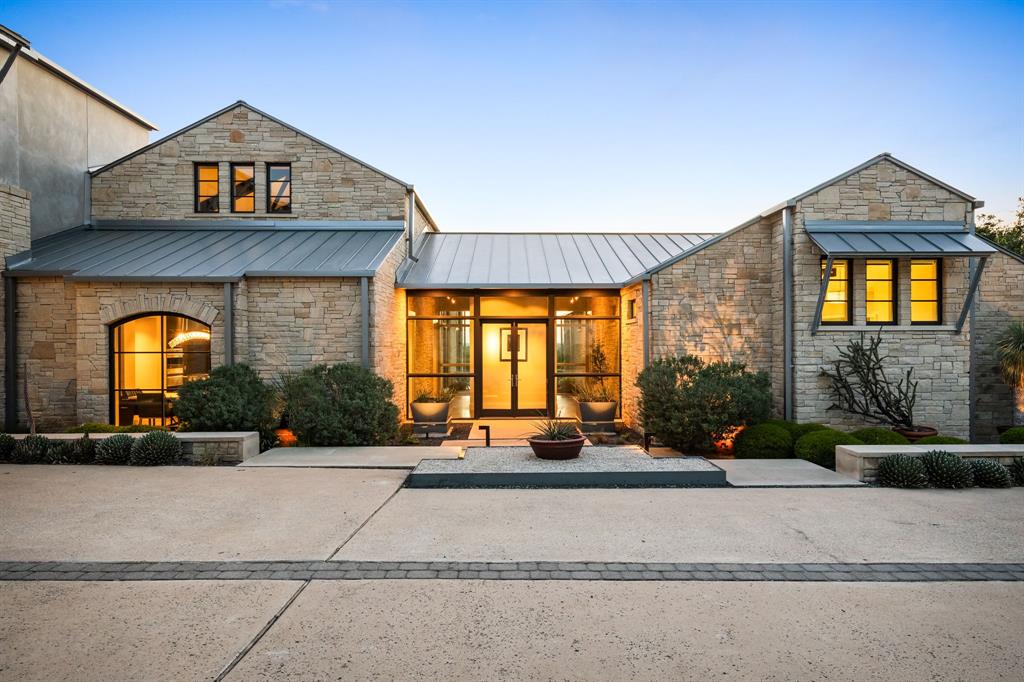
If you've owned your Austin home for a few years and are starting to think about moving into something different, one of the first questions that probably comes to mind is:
How much equity do I actually need to buy my next home?
The answer is not as simple as having a certain dollar amount of equity in your current home.
Your equity can certainly play a major role in your next purchase, but what you can afford will also depend on your income, existing debts, mortgage rates, cash reserves, the price of your next home, and whether you need to sell your current home first.
The good news is that you may have more options than you realize.
I work with a lot of homeowners who have outgrown their current home but aren't sure how to make the next move work financially. Sometimes they assume they need to sell first. Sometimes they think they need 20 percent down. And sometimes they don't realize how much equity they have built until we actually look at the numbers.
Here's what I would consider before making a move.
Your home equity is essentially the portion of your home that you own.
It's the difference between what your home is worth and what you still owe on your mortgage.
For example, let's say your Austin home is worth $700,000 and you owe $400,000 on your mortgage.
That gives you approximately $300,000 in equity.
But that does not necessarily mean you have $300,000 available to put toward your next home.
If you sell, you'll have selling expenses to account for, and you may also want to keep some money available for your next purchase, moving expenses, repairs, or other costs.
This is why I always recommend looking at your usable equity, not just the estimated value of your home minus your mortgage balance.
One of the biggest misconceptions I hear from homeowners is that they need 20 percent down to buy their next house.
That's not necessarily the case.
The amount you'll need to put down depends on the type of loan you use and your overall financial situation.
Some buyers choose to put less than 20 percent down and keep more cash available. Others prefer to put more money down to reduce their monthly payment.
There isn't one right answer for everyone.
If you're moving up from one Austin home to another, I'd want to look at the entire financial picture rather than automatically deciding that all of your equity should go toward the down payment.
This is where things get more personal.
Let's say you own a home worth $650,000 and owe $350,000.
You have approximately $300,000 in equity.
If you sell the home, you won't necessarily walk away with the full $300,000 because you'll have costs associated with selling.
But if you ended up with, for example, $260,000 after paying off your mortgage and selling expenses, that could give you quite a few options for your next purchase.
You might choose to use $150,000 toward the next home's down payment and keep the rest in savings.
Or you might decide to put $200,000 down and keep a smaller cash reserve.
Or you may have another source of funds that allows you to use even less of your home equity.
The important part is understanding what your numbers actually look like before you start shopping.
This is one of the biggest questions for move up buyers.
If most of your available cash is tied up in your current home, you may need to sell before you can comfortably purchase your next one.
That doesn't mean you necessarily have to sell first and then figure out where you're going to live.
There are different strategies that can sometimes make the transition easier.
Depending on your situation, you may be able to negotiate a longer closing, make your purchase contingent on the sale of your current home, use temporary financing, or structure the timing of the two transactions to overlap.
Every situation is different, which is why I don't believe in a one size fits all approach.
I also wrote Should You Sell Before Buying Your Next Home in Austin?, which goes more in depth on the pros and cons of selling first versus buying first.
This is actually pretty common.
You may have built significant equity in your home, but most of that money is still tied up in the property.
That doesn't mean you can't move.
It just means we need to think carefully about the timing.
For example, if you're looking at a $900,000 home and have substantial equity in your current property, the question isn't simply, "Do I have enough money for the down payment?"
We also need to consider what happens between selling your current home and purchasing the next one.
How much cash will you have after the sale?
What will your new monthly payment look like?
What are current interest rates?
What other expenses will come with the move?
And how much cash do you want to keep in reserve?
These are conversations I recommend having with your lender before you start seriously looking at homes.
When you're calculating how much money you'll have available for your next purchase, don't just look at your home's estimated value and subtract your mortgage balance.
There are costs involved with selling a home.
Depending on your situation, you may have agent compensation, title and escrow expenses, repairs, staging, moving costs, and other transaction expenses.
I go into more detail about this in What Does It Really Cost to Sell a Home in Austin?
Knowing these costs ahead of time gives you a much more realistic idea of how much you'll actually have available after the sale.
This is something Austin homeowners have to think about in today's market.
You may have purchased your home expecting significant appreciation, but the market doesn't always move in a straight line.
That doesn't automatically mean moving up isn't an option.
You may have built equity simply by paying down your mortgage. You may also have other savings or investments that can be part of your purchase strategy.
And your next home doesn't necessarily need to be dramatically more expensive than your current one.
Moving up can mean getting a different floor plan, a better location for your lifestyle, more outdoor space, a home that better fits your needs, or simply something that feels like a better long term fit.
The price difference between your current home and your next home is only one part of the decision.
This is another option some Austin homeowners consider.
Instead of selling your current property, you may be able to keep it as a rental and purchase your next home.
Whether that makes sense depends on your equity, mortgage, rental income, expenses, cash reserves, financing options, and your long term goals.
It also changes the amount of money you have available for the next purchase because you aren't accessing the equity from a sale.
It's easy to get focused on the amount of equity you have and forget about the monthly payment on your next home.
Let's say you have enough equity to make a substantial down payment on a more expensive property.
That doesn't necessarily mean the home is comfortable for your budget.
Your new payment could include principal, interest, property taxes, homeowners insurance, HOA dues, and potentially other expenses.
That's why I always recommend getting a clear picture of your purchasing power with a lender before falling in love with the next house.
Your equity tells us what you may have available for the purchase.
Your income and overall financial picture help determine what payment actually makes sense.
This is where the conversation gets really useful.
Instead of starting with, "What is the most expensive house I can buy?" I prefer to work backward.
Start with the monthly payment you are comfortable with.
Then look at your estimated equity.
Then factor in your savings, current interest rates, taxes, insurance, and other expenses.
From there, your lender can help determine a realistic price range.
If you're not sure where that range falls, How Much House Can I Afford in Austin? is a helpful place to start.
You don't have to be ready to list your house next month to start figuring this out.
In fact, I usually think it's better to start earlier.
If you're considering moving in the next six months, one year, or even a couple of years, understanding your current home's value and your potential equity can help you make better decisions.
You may realize you're closer to your next move than you thought.
Or you may realize that you want to make a few changes first.
Maybe you want to pay down more of your mortgage. Maybe you want to save more cash. Maybe your current home needs some work before selling.
Having that information early gives you time to make a plan instead of feeling like you have to figure everything out at once.
There isn't a magic number.
You don't necessarily need 20 percent equity. You don't necessarily need to have your current mortgage completely paid off. And you don't necessarily need to sell your current home before you start planning your next purchase.
What you need is a realistic understanding of your current home's value, how much you owe, what you would likely walk away with after selling, and what your next home would look like financially.
From there, you can decide whether selling first, buying first, or coordinating the two transactions makes the most sense.
Moving up to your next Austin home is exciting, but it can also feel complicated when most of your available money is tied up in the house you already own.
The first step isn't necessarily finding the next house.
It's understanding your options.
I can help you look at the bigger picture, including what your current home could potentially sell for, how that fits into your next purchase, and what questions you should be asking your lender before making a move.
You don't have to have everything figured out before you start the conversation.
Madison Swanson
Luxury Real Estate Advisor, Compass
@buyingwithmadison
Should You Sell Before Buying Your Next Home in Austin?
What Does It Really Cost to Sell a Home in Austin?
How Much House Can I Afford in Austin?
Why Isn't My Austin Home Selling? 7 Common Reasons
How to Sell Your Austin Home Faster Without Lowering the Price